Online businesses can grow faster than the systems supporting them. A store that once processed a manageable number of orders each day may suddenly face thousands of transactions after expanding its product line, entering new markets, or gaining traction through social commerce.
Recent developments in digital payments, fraud prevention, tokenization, and financial technology show how the infrastructure behind online transactions is adapting to these demands. Instead of simply moving money from a customer to a merchant, modern payment technology increasingly helps businesses manage security, transaction performance, multiple sales channels, and growing operational complexity.
For high-volume merchants, that evolution can make payment infrastructure an important part of long-term growth.
Payment Systems Are Becoming More Adaptable
Early-stage online businesses often start with relatively simple payment needs. Customers reach a checkout page, enter their payment information, and complete a purchase. As sales increase, the process can become much more complicated.
A business may introduce subscriptions, mobile checkout, multiple storefronts, or international sales. It may also need payment information to flow into accounting software, inventory tools, customer management platforms, and other systems.
That is why choosing small business credit card processing with future growth in mind can matter even before transaction volumes become large. Businesses can look beyond immediate checkout requirements and consider whether their payment setup can accommodate higher volume, new integrations, and changing sales models.
APIs are playing a major role in making that flexibility possible. They allow payment systems and other business software to exchange information automatically. Instead of manually transferring transaction data between disconnected platforms, companies can build more connected technology environments.
Payment routing is also becoming more sophisticated. Depending on the technology involved, transactions can be handled according to factors such as payment type, geography, or predefined processing rules. At scale, having more control over how transactions move through the payment environment can help businesses respond to changing requirements without redesigning the entire checkout experience.
Security Is Moving Behind the Scenes
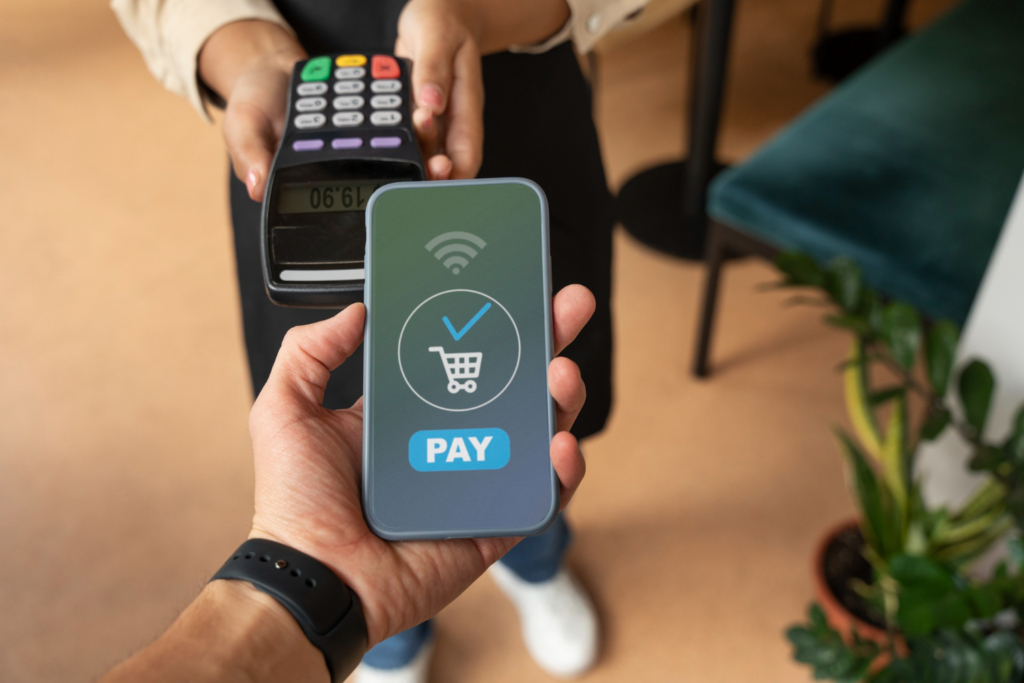
Customers expect online payments to feel simple, but a lot happens in the few seconds between clicking a purchase button and receiving confirmation.
Payment technology must transmit information securely, communicate with financial institutions, assess potential fraud, and return a decision. As digital commerce has evolved, more security tools have been built directly into this process.
Tokenization is one example. Rather than repeatedly transmitting or storing a customer’s actual card number, tokenization can replace sensitive payment credentials with a different digital value. The original information can then remain protected within the systems designed to secure it.
The PCI Security Standards Council also maintains the Payment Card Industry Data Security Standard (PCI DSS), which establishes security requirements for organizations that store, process, or transmit payment account data. Current standards address areas ranging from access controls and system security to risks associated with online payment pages.
These protections become increasingly significant as businesses scale. More transactions mean more opportunities for fraud and greater operational impact when security problems occur.
Fraud prevention technology is also becoming more automated. Instead of relying entirely on simple rules, modern tools can analyze numerous signals surrounding a transaction. The goal is to identify suspicious activity while letting legitimate customers complete purchases with as little unnecessary friction as possible.
Finding that balance matters. Blocking too little suspicious activity creates obvious risks, but aggressive controls that reject legitimate purchases can also hurt a growing business.
Automation Is Changing Payment Operations
Some of the biggest changes in payment technology are happening where customers never see them.
High-volume merchants generate large amounts of transaction information. Employees may need to monitor approvals and declines, investigate chargebacks, reconcile deposits, process refunds, manage recurring payments, and identify unusual patterns.
Automation can reduce repetitive work.
For example, connected systems can automatically pass payment information to accounting or order-management software. Reporting platforms can organize transaction activity into dashboards rather than requiring employees to assemble reports manually. Subscription tools can manage recurring billing schedules and handle failed payment attempts.
Artificial intelligence is beginning to expand these capabilities. Payment companies are exploring AI for fraud detection, transaction analysis, customer authentication, and other parts of digital commerce. AI-powered shopping agents are also emerging as a possible new participant in online transactions, raising fresh questions about how merchants will authenticate purchases and authorize automated transactions.
These developments do not mean businesses should automate every financial process. Human oversight remains valuable, particularly when transactions are unusual, disputed, or financially significant.
The more practical opportunity is to automate predictable tasks while making important information easier for people to review.
Tomorrow’s Payment Systems Will Need Room to Change
The future of online payments is unlikely to revolve around one breakthrough. Instead, several technologies are developing together.
Tokenization can reduce exposure of sensitive credentials. APIs can connect payment systems with a broader technology stack. Automated fraud tools can evaluate transactions in real time. New authentication methods can make digital purchases less dependent on manually entering card details. AI may change how consumers discover products and initiate purchases.
High-volume businesses need to prepare for that change without chasing every new technology.
The most useful payment infrastructure will likely be the kind that can adapt. Businesses should be able to add sales channels, connect new tools, strengthen security controls, and handle higher transaction volumes without repeatedly rebuilding the systems behind checkout.
For growing online companies, that flexibility turns payment processing from a basic utility into part of the technology foundation. Customers may never see most of that infrastructure, but as digital commerce becomes faster and more connected, what happens behind the payment button will increasingly shape what businesses can do next.